

For most Americans, the economy can look healthier on paper than it feels in real life.
Stocks remain near records, consumer spending has held up, and the economy is still growing. Yet housing is again becoming harder to afford, borrowing costs remain punishing, and confidence is deteriorating.
That disconnect also explains why record stock prices have done little to lift the national mood. Households with fewer financial assets experience a much smaller wealth effect while still facing high housing costs.
That said, fresh University of Michigan data show that Americans are becoming more pessimistic about current economic conditions, even as some traditional indicators remain resilient.
Housing helps explain why. Buyers have more negotiating leverage than they did a year ago, but higher mortgage rates are making the monthly payment harder to swallow.
The bigger question is whether housing is simply one symptom of that frustration, or one of the main reasons confidence is breaking down.
Housing is getting harder just as Americans lose confidence
Americans’ view of the economy tanked in early October, with the University of Michigan’s current economic conditions index falling to 44.7, its lowest reading on record.
Overall consumer sentiment slipped to 46.3, down from 48.1 in September and 53.6 a year earlier.
Survey director Joanne Hsu said “frustration over cost-of-living continues to mount,” with particularly steep declines among lower-income consumers and households with smaller stock portfolios. Year-ahead inflation expectations also edged up to 4.7%.
- Goldman Sachs rethinks U.S. economy as interest rates stay higher
- Heating bills expected to jump by $1,000 in some U.S. states this winter
- How stocks will react when the catalysts are few
Housing provides one of the clearest explanations for that frustration.
On Oct. 8, Freddie Mac said the average 30-year fixed mortgage rate jumped to 7.40%, from 7.28% a week earlier and 6.30% a year ago. It was the seventh consecutive weekly increase and the highest level since November 2023.
The market was already struggling before that latest increase.
Existing-home sales fell 2% in August to a 3.98 million annualized pace, while inventory climbed to 1.62 million homes, as reported by HousingWire. Yet the median existing-home price still rose 1.6% from a year earlier to $429,100.
I think that combination matters more than any one housing statistic. Americans are seeing more homes sit on the market and more sellers lose negotiating power, yet the cost of financing a purchase is moving in the opposite direction.
That helps explain why improving inventory has not translated into improving confidence. The deeper question is how long that contradiction can last, and what would actually have to change for affordability to improve.
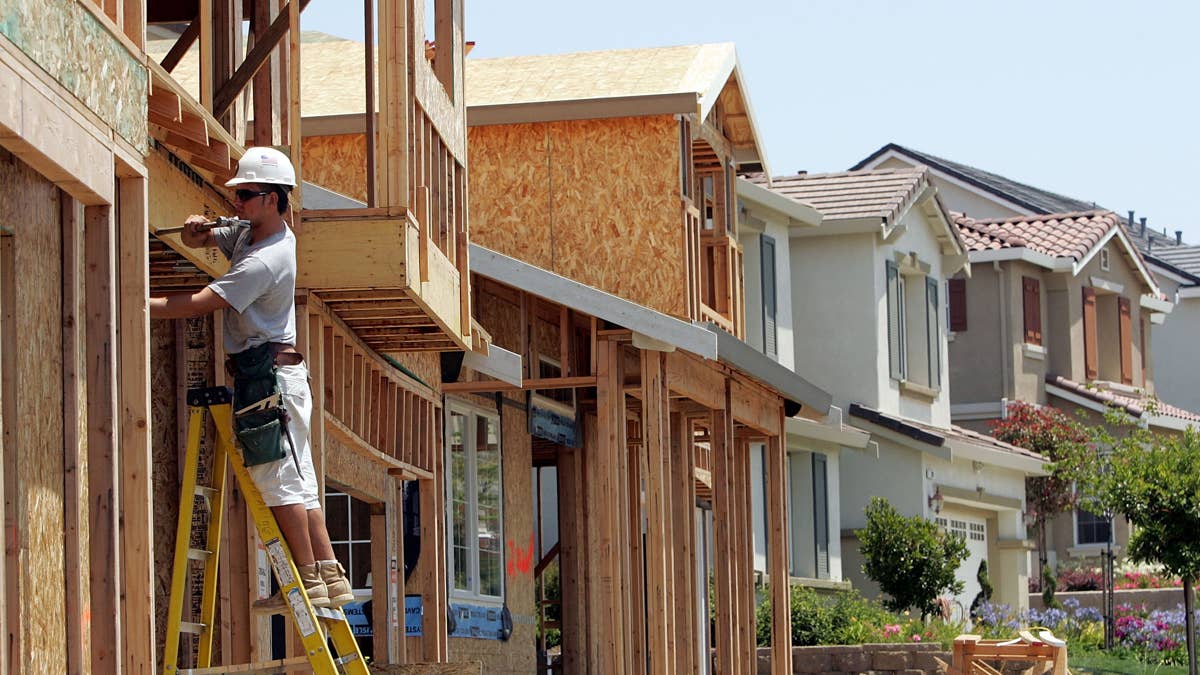
Justin Sullivan / Getty Images
Redfin’s timeline shows why housing frustration may linger
Redfin sees a path back to normal, but rates are only half the story.
Redfin’s new analysis offers frustrated homebuyers a plausible timeline for when housing costs could start to look normal again.
That said, I’d be careful with the word “normal.” Redfin defines it as the typical mortgage payment returning to 30% of household income, the national level seen in August 2018.
It doesn’t mean homes suddenly become cheap.
Under Redfin’s scenarios, mortgage rates falling to 6% while home-price growth continues around 2.1% could bring the national market back to that benchmark by November 2031. If prices instead stop rising, the timeline moves dramatically forward to February 2029.
Conversely, keeping rates between 7% and 8% while prices continue climbing could leave affordability outside that historical range for more than a decade. Redfin stresses these are scenarios, not forecasts.
That’s an important statistic because lower mortgage rates alone may not solve the problem.
Zillow CEO Jeremy Wacksman made essentially the same argument this summer, saying, “The driver of that is supply.”
Zillow estimates the U.S. remains short roughly 4.7 million homes, and Wacksman warned, “It’s not an overnight fix.”
That helps explain why affordability can remain stretched, even if borrowing costs eventually retreat. If lower rates unleash pent-up demand before construction and inventory improve enough, buyers could simply bid prices higher again.
Moreover, it makes the next question less about when housing becomes “normal” and more about which of those forces finally begins moving fast enough to change how Americans feel.
What could finally turn housing confidence around
For housing to stop weighing so heavily on Americans’ views of the economy, I think three things need to move in the same direction.
First, mortgage rates would need to fall meaningfully toward 6%, not simply ease by a few tenths of a percentage point. That would lower monthly payments and could bring some sidelined buyers back into the market.
Second, home-price growth needs to remain subdued long enough for wages to catch up. Lower rates alone could backfire if they unleash pent-up demand faster than supply improves, pushing prices higher and erasing much of the affordability benefit.
Third, inventory and construction need to expand enough to give buyers a genuine choice. That is why I would watch new listings, housing starts, and seller concessions alongside mortgage rates, rather than treating borrowing costs as the only signal.
The broader economy matters, too. Cooling inflation and a stable labor market would give households more confidence to make long-term commitments, while weaker hiring or another price acceleration could keep buyers cautious, even if financing costs improve.
To me, the clearest benchmark is therefore not simply whether mortgage rates fall. Housing confidence should begin improving when monthly payments decline relative to household income.
Until that happens, housing looks less like a side effect of weak confidence and more like one of the reasons that frustration could persist.
Related: Redfin predicts major housing market change over the next five years as debt-income ratios shift