

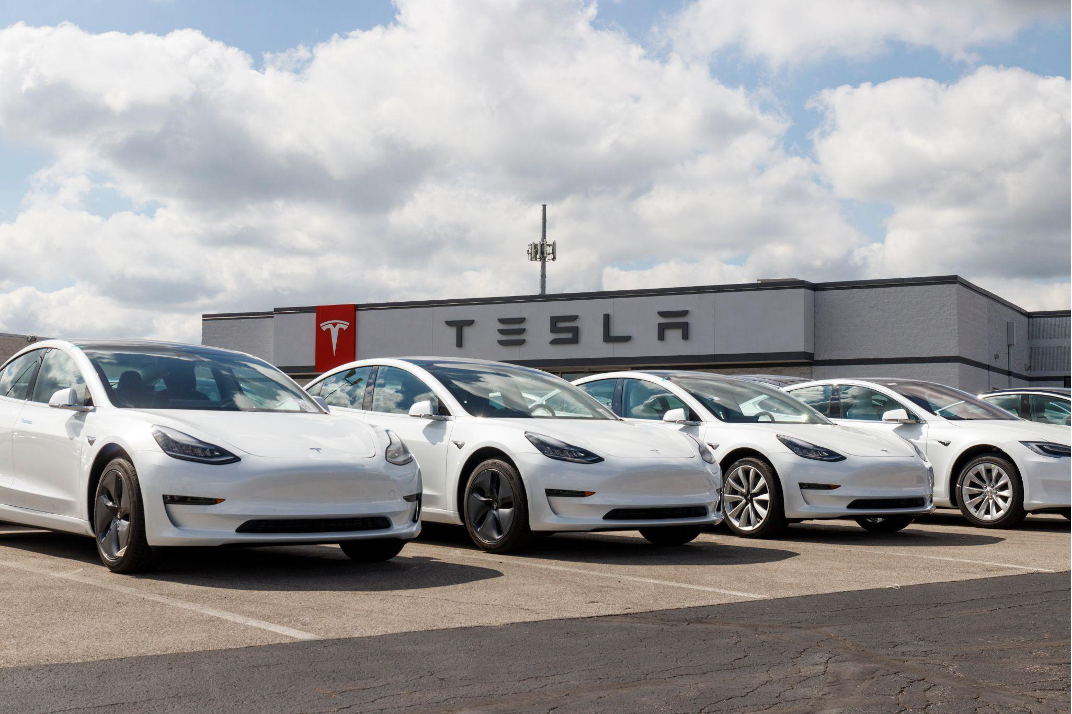
TSLA stock fell 3.62% to $372.48 in pre-market trade on Thursday, extending the decline that began when Tesla’s third quarter numbers landed after Wednesday’s close. The shares had risen 3.41% to $386.47 during the session before the print, after closing at $373.71 on Tuesday ahead of the results.
The headline number was a beat, and the market sold it inside twelve hours. Non-GAAP earnings of $0.48 cleared the $0.45 consensus, and the number management put at the center of the release was 1.74 million active Full Self-Driving subscriptions, up 67% in a year. That figure is also the one that matters most to Musk’s pay package, and Tesla does not define how it is counted, which is the part of the release TSLA stock holders should read twice.
TSLA stock ran from about $350 on 19 October to $386.48 at Wednesday’s close, then opened the gap down to $372.39 in Thursday’s pre-market once the cash flow line was read. The $0.48 beat is the part the chart does not show. Source: TradingViewActive FSD Subscriptions Reached 1.74 Million, Up 67% in a Year
The progression in Tesla’s own Q3 update deck runs 1.04 million in the third quarter of 2025, then 1.10 million, 1.28 million, 1.48 million and 1.74 million. That is 17.6% sequential growth and the best quarterly addition the company has posted, at roughly 260,000 net.
Tesla also said more than 75% of new North American deliveries included FSD in the quarter, a jump of nearly 20 percentage points from the second quarter, and that FSD miles grew about 190% year over year. On the face of it, the software attach rate is the strongest operating trend in the business and the best argument for TSLA stock at this multiple.
Tesla Does Not Say How Many of Those 1.74 Million Pay Each Month
The counting is where it gets complicated, and it is the reason the number deserves a second look before anyone prices it into TSLA stock. Electrek, which has tracked the disclosure since Tesla reported 1.28 million in April, notes the only exclusion Tesla applies is free trials. Six months on, the company still does not break out how many of those subscriptions generate a payment every month.
The distinction is not academic for anyone building a revenue model on that line. A one-time FSD purchase bundled into a vehicle sale and a recurring monthly subscription produce very different revenue profiles, and the disclosure folds them into a single line. The 75% attach rate carries the same problem, because Tesla publishes the percentage without publishing the definition.
Investor Takeaway
The 1.74 million figure is real and growing fast, but it is not a monthly recurring revenue number and should not be modeled as one in a TSLA stock valuation.
A $0.48 Beat Did Not Survive a 62% Drop in Free Cash Flow
The cash flow statement is what the market actually traded on Wednesday night. Free cash flow came in at $1.53 billion, down 62% year over year, while operating income fell to $718 million and GAAP net income to $787 million on revenue of about $28.05 billion, figures carried in the 10-Q filed for the quarter. Capital spending reached $4.73 billion in the quarter against a full-year guide of roughly $20 billion, and Reuters read the quarter as Tesla trimming spending ahead of a possible SpaceX deal.
Automotive gross margin excluding credits improved to 18.1% from 16.3%, so the core car business is recovering. The cash is leaving through Robotaxi, Optimus and semiconductor capacity faster than the margin recovery replaces it, which is why a beat produced a fall in TSLA stock. FinanceFeeds covered the full print and the bull and bear levels on Wednesday night, after the 486,532 deliveries had already beaten consensus by 24,558 vehicles.
The Merger Committee Is Tesla’s Own Disclosure Now
Tesla confirmed it has formed an independent special committee to evaluate an early-stage combination with SpaceX, with Musk excluded from its deliberations and no terms announced. That makes it a Tesla disclosure rather than something Musk said on someone else’s call, which is where it sat after SpaceX’s results on Tuesday.
Musk declined to elaborate when the question came up on Tesla’s Wednesday call. The arithmetic a deal would have to clear, including the premium Tesla holders would need, is unchanged by the committee existing, and the cash gap above is the reason the pairing keeps being raised against TSLA stock.
TSLA Stock Trades at 347 Times Trailing Earnings
At $372.48 TSLA stock carries a $1.53 trillion market value on trailing earnings of $1.18 a share, which is a price to earnings ratio of 347. TSLA stock is down 15.58% for the year and 13.30% over twelve months, even after a 13.33% gain across three months.
The gap with SpaceX is the frame worth carrying into next week and beyond. Tesla’s $1.53 trillion market value sits against roughly $2.2 trillion for SpaceX after Wednesday’s rally there, which is why the two committees are weighing an acquisition rather than a merger of equals, and it puts Tesla on the smaller side of any exchange ratio. The analyst rating and the technical read are both neutral, which leaves the next Cybercab and FSD disclosures to settle the direction.
Investor Takeaway
TSLA stock at 347 times trailing earnings is priced on Robotaxi and Optimus rather than on the car business, so the spending that cut free cash flow 62% is the thesis rather than a problem.