

This past week, Americans lost email, flights, and banking access in quick succession. A Microsoft (MSFT) outage hit email, a nationwide ground stop halted air travel, and JPMorgan Chase (JPM) customers faced a banking disruption, according to Reuters.
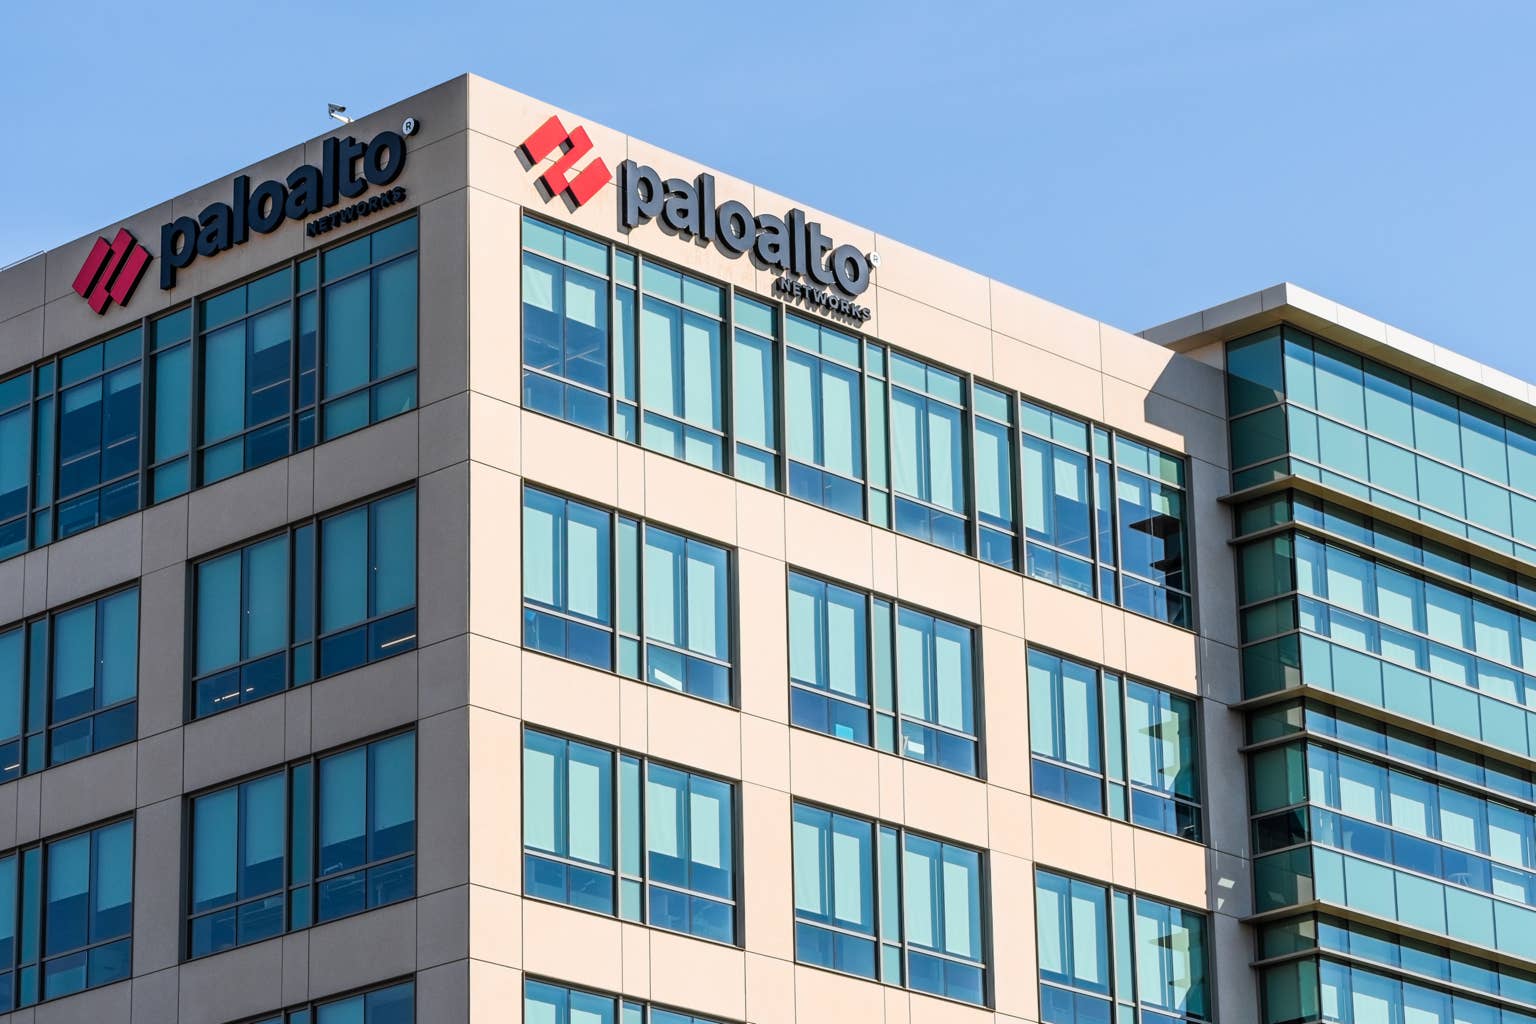
Palo Alto Networks (PANW) Chief Executive Nikesh Arora points to an unlikely source for some of that pain: the fixes themselves.
Arora made the case on Nov. 18 during the company’s earnings call. He said many recent outages were partly an accidental result of patching and configuration changes.
IT teams, he argued, cannot close a flood of new software flaws that fast without breaking things.
Washington largely agrees, with one caveat. Director of National Intelligence Jay Clayton described “separate service outages associated with maintenance and technical changes,” Reuters reported. Yet officials traced the FAA ground stop to a router installation in Arkansas, not a patch.
Also read: Palo Alto Networks CEO has a blunt warning before earnings
That diagnosis is noteworthy because Palo Alto sells the stopgap. Answering Morgan Stanley analyst Meta Marshall, product and technology chief Lee Klarich said some recent outages came from “organizations trying to move too fast on applying the patches.”
Palo Alto’s virtual patching, he explained, blocks attacks at the network while companies install the real fixes.
Morgan Stanley sees Palo Alto meeting the moment
In a note shared with TheStreet, Marshall’s team kept an Overweight rating, a $410 price target, and the stock’s top-pick status. The analysts argued that companies juggling more vulnerabilities, aging gear, and AI tools will lean on big platforms like Palo Alto’s.
Palo Alto, valued at about $283 billion according to the note, sells firewalls and security software. Revenue grew 39% last quarter, the analysts wrote, with all three segments speeding up.
The standout is Prisma AIRS, which secures how companies use AI. Morgan Stanley said it reached nearly $170 million in annual recurring revenue within five quarters, the fastest ramp in company history. Shares jumped about 9% after hours, Reuters reported.
Most of Wall Street agrees: the average target tracked by Refinitiv is about $400, just below Morgan Stanley’s, the note said. MarketBeat counts 41 Buy ratings and 11 Holds.
Not everyone is convinced. Northland Securities raised its target to $379 but kept a Market Perform rating, MarketBeat noted.
Sundry Photography / Getty Images
Some of the demand may be borrowed from tomorrow
The tougher question comes from Arora himself. Budgets for frontier AI defense, where companies probe their own systems before hackers do, “have just come out of emergency funds,” he said. Emergency cash arrives fast, but companies rarely budget it twice.
He also expects that testing to become a standard platform feature in about two years. On hardware, he conceded part of the surge came from “people accelerating purchases because prices are going up because of component pricing.”
Those costs helped push adjusted gross margin down 1.7 percentage points to 75.2%, according to Morgan Stanley. A growing mix of younger software products added to the pressure.
More Palo Alto:
- Palo Alto CEO wants AI labs out of the ‘fear-mongering business’
- Palo Alto Networks CEO drops blunt take on AI slowdown calls
- Palo Alto CEO has urgent warning for anyone using AI
A $4.5 billion bet changes Palo Alto’s cash math
That squeeze arrives as Palo Alto takes on a costlier business. It agreed to buy Applied Compute, which helps companies customize and run open-weight AI models, in a $4.5 billion all-stock deal, the note said.
Palo Alto believes the unit could add $1 billion in annual recurring revenue by fiscal 2029.
Morgan Stanley calls the deal interesting, if a little unproven, since seeing how AI models reason is a growing security issue. Still, the analysts warned it pulls Palo Alto into capital-heavy computing, with plans for more than 100 megawatts of capacity.
Arora sounded aware of the stakes: “Hopefully this is the right bet for us.”
Palo Alto expects the deal to shave up to 2 percentage points off adjusted operating margin in fiscal 2028, the note said. Its target of at least 38% free cash flow margins now excludes data center spending, which the analysts said “is not really FCF.”
Morgan Stanley’s scenarios show the range:
- Bull case of $497: Palo Alto consolidates security spending, lifting revenue to about $18.2 billion by 2028.
- Base case of $410: It gains about 0.75 percentage point of market share in two years.
- Bear case of $253: A long slowdown, weaker firewall demand, and stalled new products hit growth.
Options traders are gloomier, pricing about a 36% chance the stock falls below the bear case within a year, the note said.
Patching is turning into a market of its own
Security budgets have long been about keeping attackers out. The past week pointed to a newer cost: the disruption companies can cause themselves while racing to fix flaws that AI keeps uncovering.
Rosenblatt analyst Catharine Trebnick told Reuters that “AI tools are surfacing vulnerabilities faster than companies can patch them.” Palo Alto now profits from both ends, finding the flaws and shielding them.
The test is whether emergency budgets harden into lasting contracts once the scramble fades. Remaining performance obligations, revenue signed but not yet booked, rose 35% to $21 billion, Morgan Stanley noted.
That backlog will show whether this crisis built a lasting market or a one-time windfall.
More Stocks News
- Jim Cramer now sees a buying opportunity in beaten-down space stock
- Bill Ackman points out a problem Nvidia investors can’t ignore
- Micron CEO’s Nvidia message comes with warning for 2027
- Jim Cramer sends strong signal to Costco investors