

Morgan Stanley’s Adam Jonas doesn’t usually pitch a stock with a biology lesson. In his latest SpaceX note, though, he pointed to the human brain, which runs on about 20 watts, and to ant colonies that act as one intelligent swarm, to explain where he sees the company’s next big growth coming from.
The timing is interesting. SpaceX debuted at $135 in June, hit an all-time high of $225.64 on June 16, and has spent most of the months since trading well below that peak.
Also read: AT&T CEO holds firm stance on Elon Musk’s SpaceX phone strategy
Morgan Stanley says Wall Street is missing SpaceX’s AI swarm
Jonas reiterated his Overweight rating and $300 price target on Oct. 14. He said SpaceX’s Distributed Inference Cloud has “the greatest growth potential and is being largely ignored by investors,” and argued the topic is close to breaking out in investor conversations.
He also flagged the corporate, regulatory, and social pushback that is making traditional data centers harder to build, according to Investing.com.
The idea is to link AI agents and robots so they can share computing power across data centers on the ground and nodes in orbit. Jonas expects distributed AI and “physical AI swarms” to become a major investment theme over the next year, though the original note itself was not available for review.
Morgan Stanley thinks the market is barely paying for this. With the stock near $159 earlier this month, the bank estimated that about $127 per share came from the launch and Starlink businesses, leaving only about $32 per share for AI.
Pricing is where Jonas sees the upside. Consensus assumes SpaceX charges about $17.60 per watt for its computing capacity, yet its recent short-term contracts have reportedly been priced at $30 to $50 per watt. Every extra $10 per watt could add more than $40 billion in revenue, TheStreet reported.
Finn Gomez / Getty Images
SpaceX is quickly becoming an AI company
The numbers are already shifting. In the second quarter, SpaceX reported $7.81 billion in revenue, with about $2.56 billion coming from AI and $4.29 billion from connectivity, which includes Starlink. AI revenue grew roughly 247% from a year earlier, driven mainly by new infrastructure contracts.
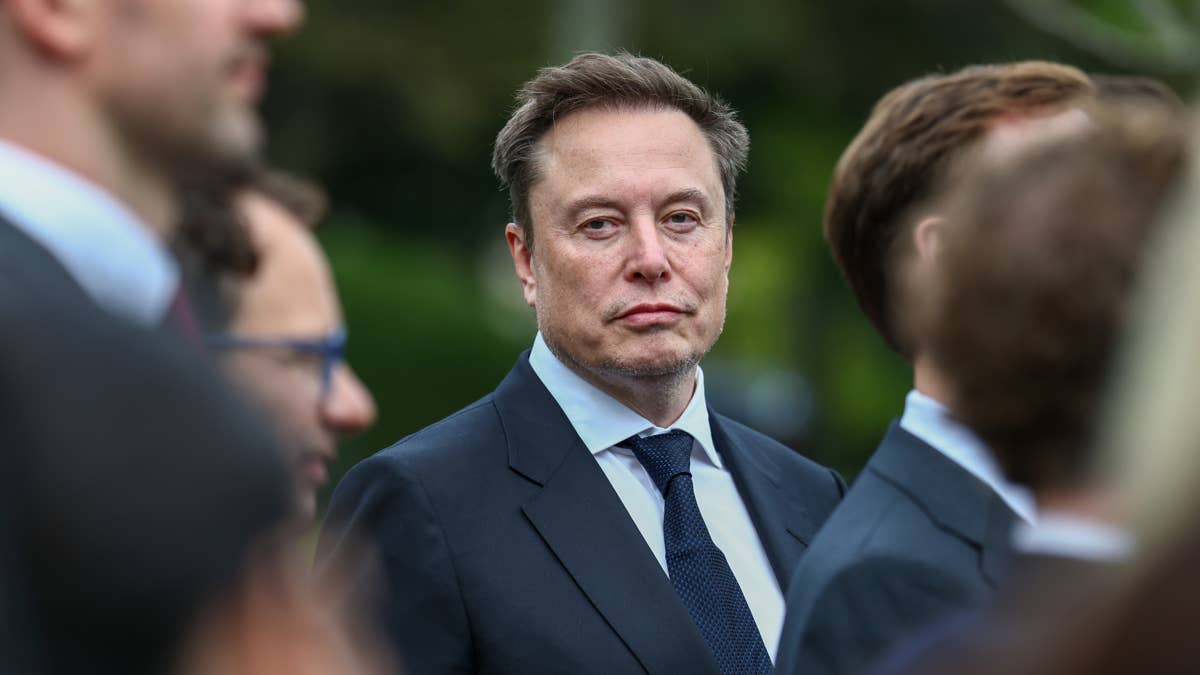
Elon Musk has been clear about where he wants the company to go. At an August all-hands meeting, he called AI an “extremely important part of SpaceX’s future” and predicted that “AI revenue will exceed all other SpaceX revenue probably in September,” according to 24/7 Wall St.
Goldman Sachs, which raised its price target to $230 from $220 in October, has also grown more bullish on SpaceX’s AI capacity and revenue prospects, 24/7 Wall St reported.
That build-out takes serious money. SpaceX is reportedly seeking $40 billion in new financing, through bank loans and investment-grade debt, to buy more Nvidia hardware.
Jim Cramer said on Oct. 7 that SpaceX “could end up being Nvidia’s largest client at this pace.” He also cited reports that SpaceX rents spare computing power to Anthropic and Google, according to TheStreet.
The AI push has deep roots. Earlier this year, SpaceX bought xAI, which the company says built the world’s first gigawatt-scale AI training cluster. SpaceX’s June IPO then raised $75 billion at a valuation of roughly $1.7 trillion, the largest public offering on record.
The SpaceX skeptics have a case
Not everyone is sold. DZ Bank analyst Markus Leistner started coverage with a Sell rating and a $100 price target, warning of “crash risk in the valuation orbit.”
He pointed to the $15.83 billion SpaceX spent on AI computing infrastructure in the second quarter alone. SpaceX still lost $541 million in that quarter, even as revenue jumped, 24/7 Wall St noted.
The valuation is another sticking point. One analyst put SpaceX at roughly 60 to 70 times its annualized second-quarter revenue. The Federal Communications Commission has also only accepted the company’s orbital data center application for filing, which starts a review but does not authorize deployment.
Astrophysicist Jonathan McDowell has questioned the plan over cooling and space debris, 24/7 Wall St confirmed.
More SpaceX:
- Goldman Sachs revamps SpaceX stock estimates before crucial earnings test
- Musk called Anthropic ‘evil’; SpaceX’s deal with it nearly doubled
- Morgan Stanley doubles down on SpaceX stock verdict for investors
Even Jonas has a bear case. If AI momentum slows, Starship hits a serious testing wall, or SpaceX needs a large equity raise, he said the stock “could slide toward $100 within 12 months.” Higher computing costs and delays in connecting data centers to power are also on his risk list.
Share supply is another overhang. Further lockup releases are set to free up more stock, including about 28% of locked shares after the third-quarter report, while Musk’s own stake remains locked until June 2027. Short interest reached roughly 31% of the float in early July, according to 24/7 Wall St.
What SPCX investors should watch next
Starship is the near-term swing factor. Flight 15 is expected in late October or early November, with the third-quarter earnings due around the same time. Jonas said a successful Starship catch “could be the biggest positive catalyst for the stock since its IPO.”
Starlink’s mobile ambitions are drawing attention, too. Pivotal Research raised its price target to $230, citing SpaceX’s $8 billion deal for Grain Management’s nationwide 800 MHz spectrum. This still needs approval from the Federal Communications Commission and the authorization of 15,000 direct-to-device satellites. TD Cowen also reiterated its Buy rating.
Even fans are trimming. Cathie Wood’s ARK sold roughly $8.5 million of SpaceX stock on Oct. 6, according to The Motley Fool. Though ARK built the position over the summer, the move looks more like portfolio rotation than a bearish call.
For now, Jonas is betting the swarm story wins out over the skeptics.
Related: Elon Musk makes an audacious claim on the growth of SpaceX