

Every sneaker shopper knows where unsold shoes go. They land on the clearance rack, marked down until someone buys them.
That rack is the hidden risk inside Nike Inc.’s (NKE) first-quarter report on Thursday, Oct. 1, 2026. The company beat profit estimates. Investors sold the stock anyway.
Morgan Stanley thinks investors read it right. The quarter was “likely the year’s high-water mark,” according to a Morgan Stanley note sent to TheStreet. The bank expects the rest of Nike’s fiscal year, which ends in May 2027, to look worse.
Nike’s own forecast agrees. The company expects fiscal 2027 revenue to fall by a high single-digit percentage, according to its earnings release. Analysts had expected a gentler decline of about 2%, according to Reuters.
Read More: Nike lost its blue-chip badge but not its swagger
Nike’s earnings beat leaned on retailers, not shoppers
Nike earned 48 cents a share, ahead of the 44 cents Wall Street expected, Morgan Stanley noted. The bank’s concern is where the revenue came from.
Nike’s sales to retailers in North America rose 9%, according to the release. Meanwhile, Nike Direct, its own stores and apps, shrank in every region.
That split is very important. A wholesale order proves a store bought the shoes, not that a customer wanted them.
Morgan Stanley’s channel checks flag that gap, a risk the bank says Nike management has acknowledged.
If shoes don’t sell, retailers sit on extra inventory, and the discounts needed to clear it could hurt the brand for years, the note warns. The clearance rack may be where this quarter’s beat ends up.
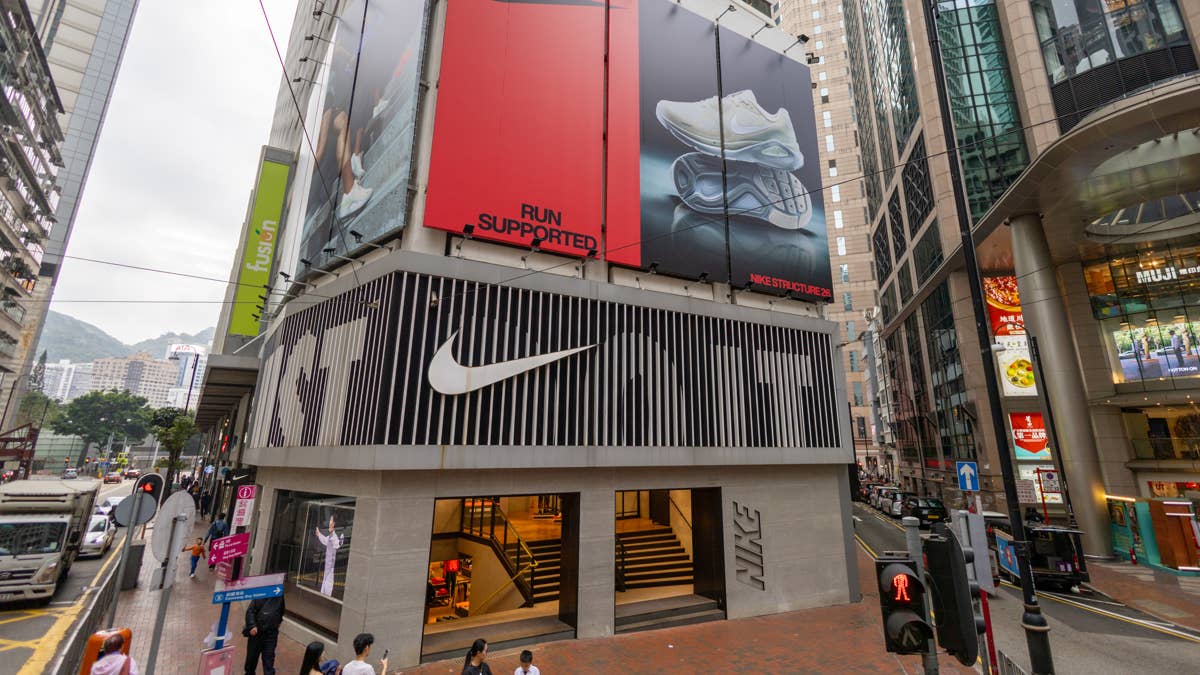
winhorse / Getty Images
The rest of Nike’s fiscal year gets harder
Nike’s guidance implies earnings per share falling roughly 50% over the final three quarters at the midpoint, according to the Morgan Stanley note. First-quarter earnings, in contrast, slipped only 2%.
The bank cut its fiscal 2027 earnings forecast by more than 30%, to $1.15 a share, the bottom of Nike’s guided range.
Nike’s fix is Pace, a restructuring program expected to save about $2.5 billion through fiscal 2031, according to the release. Most of those savings land in fiscal 2029 and 2030, according to Reuters. That leaves little cushion this year.
“We have more work to do in NIKE Sportswear, Jordan Brand and Greater China,” CEO Elliott Hill said in the release.
Pace also means more layoffs, with job decisions starting in 2027 after two rounds of cuts this year, CNBC reported. “Nike is turning into a cost-cutting story,” Citi analysts wrote, according to CNBC.
Nike stock sits at a 13-year low with few believers
Nike owns the Swoosh, Jordan, and Converse, and its stock has long traded as an untouchable blue chip. That reputation is gone.
Shares trade at their lowest level since 2013, down about 45% this year. The slide deepens the worst drawdown in company history and follows Nike’s S&P 100 exit in September.
More Nike:
- Nike just got kicked out of an elite club
- Nike is selling $80 casual sneakers for only $50
- Bank of America drops bombshell verdict on Nike stock
The 42 analysts tracked by Stock Analysis rate Nike a consensus Hold, with an average price target near $41. Strong Buy ratings have dropped from 15 to nine since April, a sign that conviction is fading.
Notes on Friday, Oct. 2, 2026, kept that tone. Morgan Stanley cut its price target to $27 from $31 and kept its Underweight rating. Citi stayed neutral, arguing that Nike deserves no premium valuation over growing rivals, according to CNBC.
DZ Bank downgraded the stock to Sell, according to Stock Analysis. Jefferies stayed at Buy but cut its target to $60, a sign even the bulls are recalibrating.
Valuation is Morgan Stanley’s sharpest point. Even after the post-earnings drop, Nike traded near 26 times expected earnings, above its 10-year average of about 24 times, the note shared. Its own work suggests a multiple closer to 16 times, implying a stock price near $20.
Income investors face a quieter problem. Nike’s 41-cent quarterly dividend adds up to more per year than its adjusted earnings guidance. With $8.4 billion in cash and short-term investments, the payout looks safe for now, but the margin for error is thin.
Big sportswear brands no longer get a scale premium
For decades, scale was Nike’s biggest advantage. It could outspend rivals for athletes, shelf space, and advertising.
That edge is fading. Morgan Stanley rates Swiss rival On Holding (ONON) Overweight and Nike Underweight, according to the note. In September, Kylian Mbappé left Nike after two decades and joined On, Reuters noted.
The next test is Nike’s investor day on Nov. 16 and 17, where management will lay out a five-year financial outlook, according to Morgan Stanley. The bank wants to hear the “right” size for Sportswear, Jordan, North America, and China.
Nobody asked that question in 2021, when Nike’s stock hit its record high. Now it may be the most important number investors hear: not how fast Nike can grow, but how much smaller it must become first.
More Stocks News
- How much Nvidia stock does CEO Jensen Huang actually own?
- Bank of America resets Micron stock forecast as AI ‘memory tax’ rises
- Popular dating platform Grindr makes surprising healthcare move
- Jim Cramer spots overlooked AI stock after $11.6 billion deal