

If you are already putting money into a 401(k) or a Roth IRA every month, you are ahead of most Americans. About four in 10 people have nothing invested in a retirement account of any kind, according to Gallup.
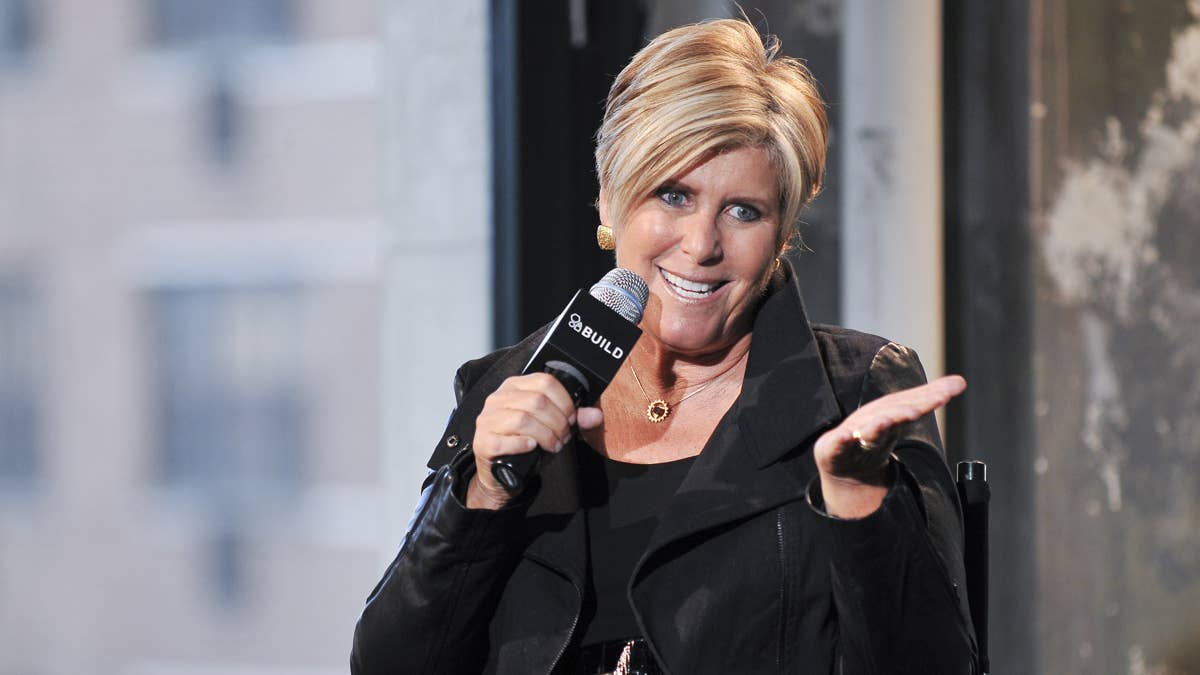
But having a plan on autopilot is not the same as being prepared, and financial expert Suze Orman says the people who feel like they have retirement handled are exactly the ones she is most concerned about heading into 2027.
In a recent post on her website, Orman urged readers to raise their 401(k) contribution rate by one to two percentage points before the new year and to max out a Roth IRA if eligible.
She framed it as preparation for three financial shocks she says hit harder than most savers expect, and that can undo years of steady contributions at the worst possible time.
These are not edge cases. They are common life events that tend to land in your 50s and 60s, when retirement feels close enough to count on.
Here is what Orman says you need to be ready for.
Also read: Suze Orman says a $1.6 million retirement tax move could backfire
Waiting to save more costs more than you think
Time is the one variable you cannot buy back. A dollar saved in your 20s and 30s has more time to grow than a dollar saved in your 50s, Orman said.
If you wait until 45 to increase your contributions instead of starting at 35, you do not just lose 10 years of deposits. You lose 10 years of growth on every dollar you already have saved.
Raising your 401(k) rate by one percentage point is not a dramatic change. Most people will not notice it in their take-home pay, particularly after a raise. Orman has made this case before: A small monthly gap in savings compounds into a large shortfall by retirement.
“It has always been risky to assume you don’t need to save much when you are younger,” she wrote. “But what is very much in your control right now is committing to saving even more for retirement when you are young.”
Jenny Anderson / Getty Images
Caregiving can cost you $11,500 a year out of pocket
Most people’s retirement plans do not include a line for caring for an aging parent or an ill spouse. They probably should.
A Northwestern Mutual study indicated that 39% of Americans are or have already been caregivers, and 56% believe they will take on that role at some point. Caregiving is not a fringe risk. It is the likely reality for most households.
Out-of-pocket costs for family caregivers have risen nearly 60% since 2021, averaging $11,508 a year, which is about 31% of the typical household’s income, according to AARP.
Sixty-five percent of working caregivers said they experienced at least one work-related disruption because of it. When professional care enters the picture, costs go higher.
The median monthly cost of assisted living was $6,200 a month in 2025, and a private nursing home room averaged $10,798 a month, according to CareScout’s Cost of Care Survey.
“If you eventually need to step in and help a loved one, you will already be further ahead with your retirement savings,” Orman wrote.
People who pull back from work in their 50s and early 60s to provide care often do so at the peak of their earning years. That is also when they should be making their largest retirement contributions, meaning that the financial cost of caregiving runs well past the direct expenses.
Supporting your adult kids could set back your retirement
Nearly one in three adults between the ages of 25 and 34 were living with their parents in 2025, according to a Realtor.com report. About 70% of them are employed.
The issue for most is not joblessness. It is that rent and housing costs have outpaced what entry-level and mid-career wages can cover, and parents are making up the gap.
More Retirement:
- 20 million Medicare beneficiaries may get a one-time $90 payment
- Vanguard spotlights Roth IRA trap hiding in your income
- Dave Ramsey raises a $185K risk Fidelity pegs for retirees
Seventy-one percent of parents said they have financially supported an adult child, according to a LendingTree survey. Sixty-four percent said it caused them financial stress. Eleven percent said it set back their retirement planning.
“I will never condone helping an adult child if it puts your retirement at risk,” Orman wrote.
You can borrow for a car or a house. You cannot borrow for retirement. Every dollar you redirect from your 401(k) to cover your adult child’s expenses is a dollar that stops compounding, and you do not get that time back.
Nearly half of workers fear a layoff within 12 months
Saving more later only works if you still have an income later. Forty-four percent of surveyed workers said they worried an economic downturn could cost them their job within the next 12 months, according to the American Psychological Association‘s 2026 Work in America survey. Another 32% said they worried about losing their job within weeks or months.
Layoffs are not the only way a career ends early. Health problems, family obligations, and burnout do the same thing. A 2025 EBRI survey found that about 40% of retirees retired earlier than planned, and nearly 70% of those said the reason was out of their control.
If you plan to save heavily in your late 50s but leave the workforce at 57 instead of 65, you lose eight years of contributions, along with the compound growth that would have built on them.
These small money habits build a bigger retirement cushion
You do not need to overhaul your budget to save more. Raise your 401(k) contribution by 1%, then raise it again after your next pay increase.
Start by contributing at least enough to get your employer’s full match. Unmatched contributions leave free money behind before you have done anything else.
Go through your fixed monthly charges and cut what you are not using. Streaming subscriptions, auto-renewing apps, and forgotten memberships add up. Put that money into a Roth IRA or a health savings account instead.
A tax refund or a bonus is another place to look. Rather than absorbing it into everyday spending, put a portion directly into an IRA before the contribution deadline.
The 2027 IRA and 401(k) contribution limits have not yet been announced. For 2026, the IRA cap was $7,500 for savers under 50.
When the 2027 figures are released, Orman’s advice is to get as close to the maximum as your budget allows.
Related: New Social Security bill seeks to lower retirement age