

One of Wall Street’s highest-profile hedge fund managers held a major technology position for barely three months before selling it.
Bill Ackman, Founder and Chief Executive Officer of Pershing Square Capital Management, bought Alphabet shares in the first quarter and sold all by June 2026.
The more revealing move is where Ackman sent the money, as Pershing Square used its Alphabet proceeds to increase its stake in a direct competitor.
The fund increased its Meta Platforms position by roughly 20% during the second quarter of 2026, according to Pershing Square’s 13F filing, reported by Seeking Alpha.
That swap has looked increasingly well-timed, as the two stocks have moved in opposite directions so far in the third quarter.
Pershing Square’s second-quarter moves went wider than Alphabet
Ackman’s full exit from Alphabet was part of a broader portfolio overhaul that Pershing Square executed during the second quarter of 2026.
The fund disclosed fresh positions in Visa, Mastercard, S&P Global, and Netflix, committing billions in new capital across payments and entertainment, Seeking Alpha showed.
Meta ranked as the seventh-largest position in Pershing Square’s concentrated 14-stock portfolio at the end of June 2026, sitting alongside top holdings Uber Technologies, Brookfield Corporation, Microsoft, and Amazon.
Selling every Alphabet share shows that Pershing Square sees near-term trouble for the company.
Meta has returned more than 19% since the second quarter ended, while Alphabet has slipped into negative territory in the same period, according to Motley Fool data.
The performance gap has widened in September 2026, driven largely by one product launch that gave Meta a narrative Alphabet has struggled to match this year.
Meta’s Muse launch gives the stock a catalyst that Alphabet currently lacks
Meta’s third-quarter rally traces directly to a single product debut that Wall Street is now pricing into forward earnings estimates and research models.
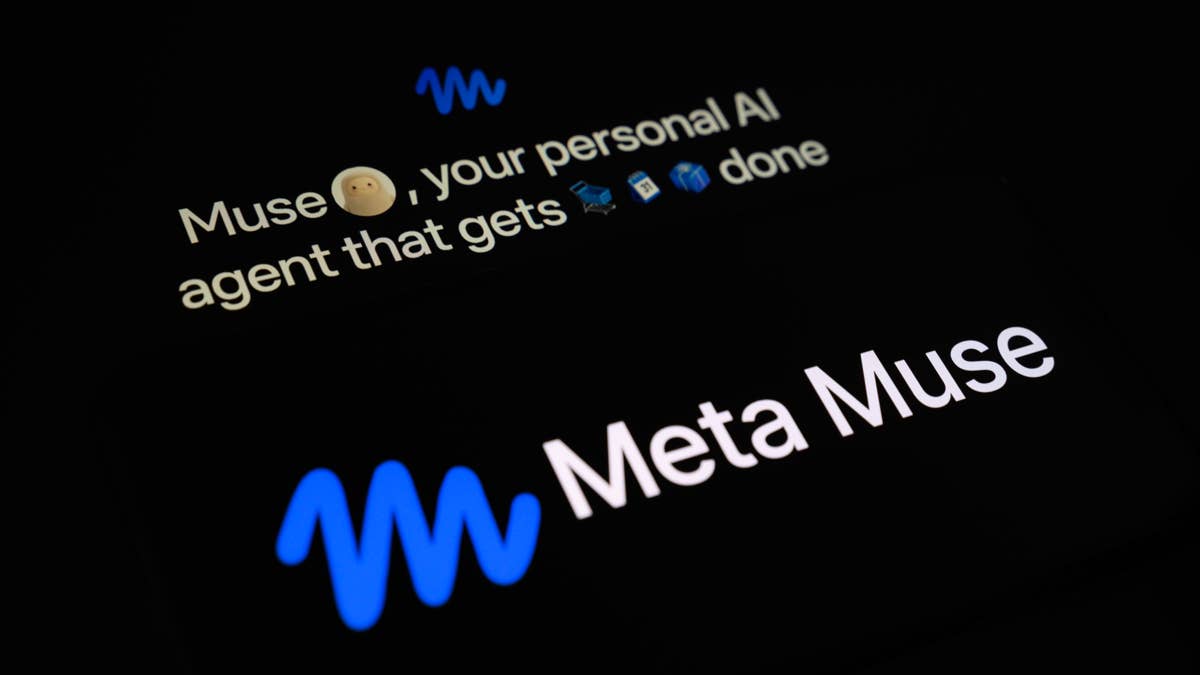
The company launched Muse, a personal artificial intelligence agent, on September 8, 2026, and early adoption outpaced internal expectations by a wide margin, BigGo Finance reported.
The agent handles everyday tasks by connecting to a user’s email, calendars, payments, and apps for health, smart home, shopping, and dining.
Muse is free at a basic level, with paid subscription tiers at $20 and $100 per month for heavier task delegation, TechCrunch noted.
Doug Anmuth, Managing Director and Internet Analyst at JPMorgan, pointed to Muse reaching as high as the third spot in the U.S. App Store on its second day, with early usage running at roughly 10 times that of internal training cohorts, Guru Focus reported.
Doug Anmuth upgraded Meta Platforms to Overweight on September 10, 2026, with an $820 price target, and reported on CNBC that consumer artificial intelligence products, still in their earliest commercial stages, could open revenue channels the market has not yet priced in.
<strong>We believe there's still meaningful upside potential as Meta is in the early stages of releasing frontier models and AI-driven products beyond advertising, notably Muse AI agent and Meta Model API access</strong>
That rapid consumer adoption provided Wall Street with concrete evidence for a thesis that Meta’s artificial intelligence products could extend the company’s growth runway beyond advertising.
Meta’s second-quarter revenue reached $60.8 billion, a 28% year-over-year gain that reinforced the case for its accelerating advertising engine, the company’s earnings press release confirmed.
NurPhoto / Getty Images
Anmuth’s upgrade puts Meta’s AI runway ahead of Alphabet
Alphabet’s negative third-quarter stock performance reflects a company weighed down by two concurrent pressures that could stretch well into 2027.
A federal court entered a final judgment against Google in December 2025, imposing restrictions on the distribution of search products and requiring data sharing with competitors, Alphabet’s 10-Q filing confirmed.
Alphabet appealed the ruling in January 2026, while the Department of Justice (DOJ) and state attorneys general filed their appeal the following month, the filing noted.
More AI:
- Nvidia just made a move Wall Street wasn’t ready for
- Microsoft just took sides in the AI policy fight
- OpenAI just disclosed something genuinely alarming
Anat Ashkenazi, Senior Vice President and Chief Financial Officer of Alphabet, said on the July 22 2026, second-quarter earnings call that Alphabet raised its full-year 2026 capital expenditure guidance to a range of $195 billion to $205 billion.
This is up from $180 billion to $190 billion, mostly directed toward artificial intelligence and cloud infrastructure.
That spending pressure on free cash flow, combined with unresolved antitrust remedies that could stretch into 2027, helps explain why Alphabet has not kept pace with Meta’s recent rally.
What Meta’s persistent valuation discount signals for investors
Despite Meta’s sharp third-quarter rebound, it still trades at roughly 20 times forward earnings, below Alphabet’s forward multiple of 23 times, GuruFocus data showed.
That discount persists even as Anmuth argued Meta’s distribution to 3.6 billion users gives it a competitive edge few rivals can match.
Anmuth cautioned that Muse’s monetization is not a near-term priority, which means the agent’s contribution to Meta’s revenue remains unproven at this stage, CNBC reported.
The key variable his analysis leaves open is whether Muse retains users past the initial download surge and generates repeatable subscription revenue.
Muse’s ability to convert early traction into durable subscriber revenue will shape whether Meta’s discount to Alphabet continues to narrow into 2027, Anmuth’s analysis suggested.
Related: Bill Ackman’s Pershing Square invests $1.1B in fintech giant