

One thing I’ve learned from watching the stock market is that a great company doesn’t always make a great investment at every price.
I’ve seen investors fall in love with a stock’s potential, only to watch those big expectations collide with reality. And when the excitement fades, the drop can be brutal. I think investors are getting a painful reminder of that lesson from Rocket Lab (RKLB).
Rocket Lab hit an all-time high of $151 on May 27, according to Yahoo Finance, primarily driven by explosive Q1 2026 earnings, a record-breaking multi-billion-dollar backlog, and aggressive Wall Street price target upgrades based on expanding satellite construction contracts for the U.S. government.
As of writing, shares trade at $53.35 on Oct.16 — a 64.9% decline — for a couple of reasons. Now, Jim Cramer has delivered a blunt verdict on the struggling space stock after an Oct. 14 problem, during CNBC’s “Mad Money” Lightning Round.
I thought the failure to launch would've hurt it more. I think you're getting a great opportunity to sell, sell, sell.
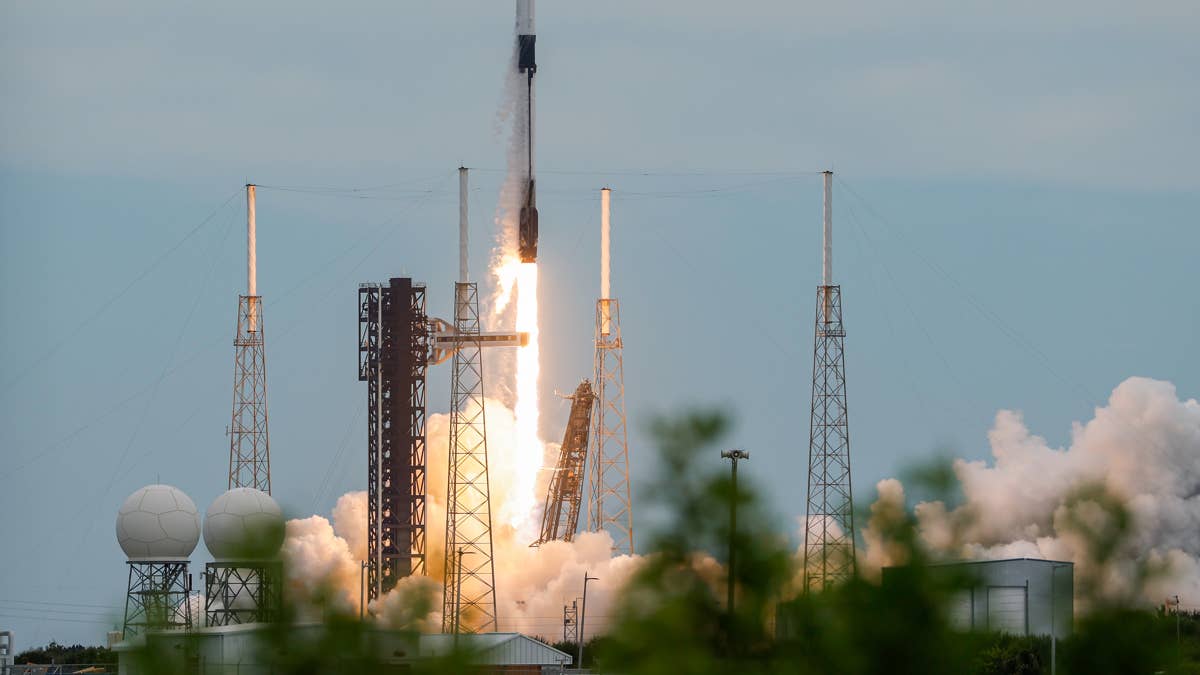
The “failure to launch” he’s referencing is an engineering problem that has now delayed Rocket Lab’s Neutron rocket three times.
Also Read: Rocket Lab Inc.Latest News
The Rocket Lab delay that broke the bull case
On Oct. 14, Rocket Lab filed an 8-K form with the SEC disclosing that engineers discovered voids, small air pockets, in the carbon-composite forward dome of Neutron’s first-stage propellant tank. The structural flaw requires a full redesign and process changes.
First launch is now formally pushed to 2027, according to the filing.
For context, Neutron was originally targeted for 2024. Then 2025. Then late 2026. Now 2027. Each slip has been framed as manageable.
The cumulative effect is that a rocket which was supposed to be flying while competitors were still drawing blueprints is now three years past its original schedule with no hardware in the air.
More Rocket Lab:
- Rocket Lab stock moves on solar cell announcement
- Rocket Lab clears 1st hurdle in its biggest satellite deal
- Why Rocket Lab is becoming a bigger defense player
That timeline matters because of a specific financial trigger CFO Adam Spice had once communicated to investors. A successful Neutron test flight was the key catalyst for Rocket Lab to turn positive on adjusted EBITDA the following quarter.
Without Neutron flying, that profitability milestone moves into the uncertain future.
Compounding the sentiment damage, Spice sold approximately $9.9 million in shares under a pre-arranged trading plan in early October, according to The Motley Fool, creating an insider-selling overhang that algorithmic traders read as a ceiling signal. The 8-K landed the next week.
The macro that made a bad week worse
Even a clean 8-K would have landed in difficult conditions. September CPI came in above expectations at 3.7% year-on-year, reigniting fears of additional Federal Reserve rate hikes and pushing Treasury yields higher, according to the Bureau of Labor Statistics.
High-growth, loss-making companies like Rocket Lab are particularly exposed to rising yields. Their valuations depend on discounting cash flows projected years into the future.
When rates rise, the discount rate rises, and those future cash flows become worth less today. The mathematical effect on premium-multiple growth stocks can be severe. And it was.
I remember covering RKLB in May when the stock surged past every Wall Street price target after a record earnings beat. Q1 2026 revenue was $200.3 million, up 63.5% year over year, against a backlog exceeding $2.2 billion.
It felt like a company that had finally broken through the noise. The problem with breaking through the noise is that when things go wrong, the noise comes back louder.
Justin Sullivan / Getty Images
What Rocket Lab’s business actually looks like right now
The important distinction Cramer’s call raises is whether Rocket Lab is broken or Neutron is delayed.
The underlying Electron small-launch business continues to perform. On earnings, most recent quarterly revenue was $234 million, according to its Q2 earnings results, against $257.76 million expected for the next quarter, according to consensus estimates.
Rocket Lab has continued expanding its business, including signing a 20-mission contract with Synspective. But that growth comes at a cost.
Its $8 billion acquisition of Iridium Communications, as part of its push to challenge Starlink, was partly funded through a $1.944 billion equity offering. That added roughly 29.3 million new shares, diluting existing shareholders and putting additional pressure on the stock.
The balance sheet offers some reassurance, with cash exceeding debt, according to Yahoo Finance. Still, profitability remains out of reach this year, while elevated revenue and price-to-book multiples leave little room for disappointment.
Cramer’s read is that the stock has not yet fully priced in a third Neutron delay. “I thought the failure to launch would’ve hurt it more” is his way of saying the market was more resilient than it should have been, and that the realistic reset is still ahead.
The next potential catalyst is Rocket Lab’s earnings report, expected around Nov. 9. We will be watching for progress on Neutron’s redesign, Iridium integration, and Electron’s growing backlog.
Without meaningful progress on those fronts, the bull case could remain full of promise but still waiting on the launchpad like Neutron itself.
More Stocks News
- Michael Burry just made another bold move on Wall Street
- IBM spent $11 billion on growth as its own software stalls
- UBS resets Microsoft stock price target for investors
- Boeing lands key role in future of U.S. air power