

The first market move was about uncertainty
As results came in, US stock futures fell, Treasury yields declined and the dollar weakened. Nasdaq-100 futures dropped as much as 2.4% and S&P 500 futures fell 1.4% before recovering. The dollar reached a one-month low and gold moved above $4,000 as investors considered greater scrutiny of AI companies and data-centre projects.
Technology shares were an obvious pressure point. Democrats have raised questions about the power consumption, local costs and concentration associated with large data centres, and a newly empowered Congress can hold hearings, demand documents and shape the public debate around the sector. But oversight is not the same as an immediate ban on projects or a law that reverses current investment. The reaction was therefore driven partly by the risk of slower approvals and greater regulatory uncertainty, rather than a confirmed change in the operating environment for AI companies.
Markets later recovered from their lows as investors considered the limits of divided government. Democrats control committees and the legislative calendar, but Trump retains veto authority and Senate procedures remain a constraint. Gridlock may prevent abrupt policy changes while prolonging uncertainty around budgets and regulation.
Trump’s political loss does not erase executive power
The incoming Congress will be able to scrutinize the administration more aggressively, conduct investigations and prevent legislation from advancing. It can also reject some nominations and use committee control to force disclosures and public testimony. That matters for sectors affected by federal regulation, technology policy, energy and trade. Yet presidential power remains substantial. Trump can continue using executive authority in areas where the law permits, and he can veto bills passed by Congress.
The practical balance will depend on the issue. Measures requiring new legislation may stall, while decisions that rest on existing statutes or executive discretion could remain within the White House’s reach. Companies will have to separate policies that can be reversed by administrative action from those that require Congress. The election outcome changes the political environment, but it does not answer how courts, agencies or state governments will respond to future decisions.
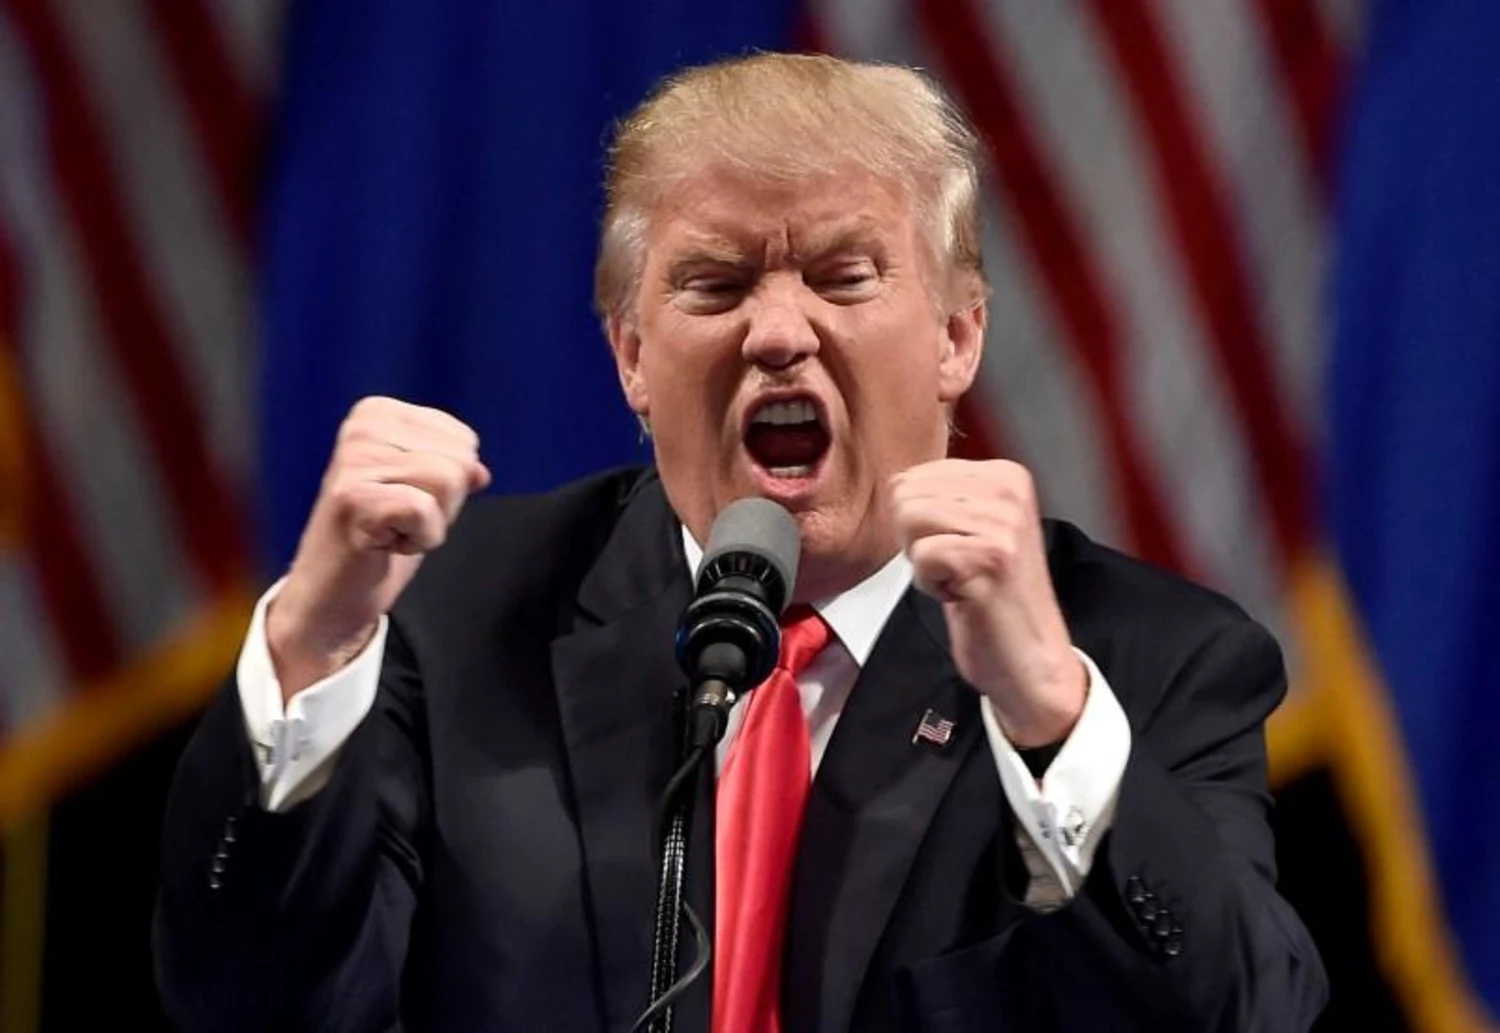
Trump congratulated Democrats and said he would work with them, while warning that he could veto legislation. He also acknowledged that the Iran war contributed to the result. Whether he will compromise or rely more heavily on executive authority remains unclear.
Markets are separating the vote from the economic outlook
The dollar’s decline reflected worries that tighter scrutiny of AI could slow investment and weaken the growth outlook. Gold gained as the dollar and yields fell. Bonds also rose as investors considered the possibility that divided government would constrain fiscal stimulus. But strategists cautioned that the result did not automatically alter the near-term economic outlook, because the new majority cannot easily enact sweeping legislation over a presidential veto.
That distinction leaves markets focused on data and rates. The October US jobs report, due Friday, November 6, at 8:30 a.m. ET, may be more consequential for the next move in the dollar and Treasuries than the final seat counts. Payroll growth and wage trends will feed into expectations for Federal Reserve policy. If the labor market remains firm, yields could recover and support the dollar; signs of a sharper slowdown would reinforce the view that growth risks are rising. Gold’s move above $4,000 also leaves the metal vulnerable to a reversal if yields rise again.
Investors will watch for evidence that data-centre projects are delayed, cancelled or repriced before treating election-night concerns as an earnings trend. A sustained slowdown would affect technology suppliers, utilities and power infrastructure. Political debate can change expectations before cash flows.
The election changes political risk, not every market rule
For Trump, the outcome weakens his ability to translate his agenda into legislation and gives political opponents a stronger platform to challenge the administration. It also makes the final two years of his term more constrained, especially if Democrats use their committee control to keep attention on policy decisions and executive conduct. The defeat does not remove his authority, and it does not predetermine the 2028 presidential contest. It changes the balance of power in Washington now.
For investors, the useful question is not whether Trump has lost politically—he has—but which decisions can now be blocked, investigated or delayed, and which remain within the administration’s control. The immediate repricing captured uncertainty around AI, the dollar and yields. The more durable market consequences will emerge through legislation, regulatory action, project approvals, fiscal negotiations and the economic data that shape interest rates.
Takeaway: Trump’s midterm defeat delivers a Democratic Congress and a more constrained final two years, but markets are not treating it as an immediate reversal of the administration’s policies. The initial technology and dollar selloff gave way to a more measured view of divided government; payrolls, yields and evidence of actual policy change will determine whether that adjustment lasts.